Related Articles
Economic conditions can influence household budgets through prices, wages, employment, housing costs, taxes, savings, and borrowing. The effects can differ considerably between households because income, employment status, mortgage arrangements, family size, and spending patterns are not identical.The Office for Budget Responsibility currently expects UK economic growth to strengthen from 2027. Its March 2026 forecast projected average real GDP growth of 1.6% annually from 2027 through 2030. However, the outlook still contains significant uncertainties.
Understanding potential household impacts requires looking beyond headline economic growth. Inflation, earnings, employment, interest rates, taxation, and public services can all affect household finances during 2027.However, households could still face substantial costs for housing, food, transport, energy, insurance, and other essential services. Individual experiences will depend heavily on income and spending patterns.
1. Household Budgets Could Remain Under Pressure
Household budgets may continue feeling the effects of earlier increases in living costs. Even when inflation decreases, prices do not automatically return to previous levels. A lower inflation rate means prices are generally rising more slowly, rather than becoming cheaper.The OBR’s March 2026 forecast expected CPI inflation to reach 2% from 2027 onwards. This represents a significant improvement compared with higher inflation experienced previously.
2. Real Income Growth Could Remain Modest
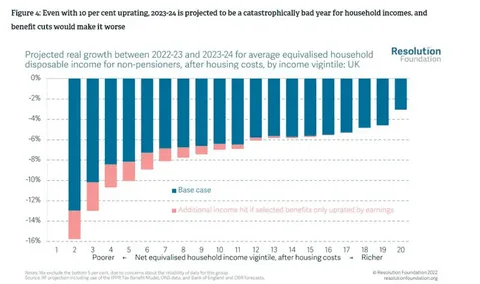
Real household disposable income measures the purchasing power households have after accounting for income and prices. This indicator can provide useful information about changes in household living standards.The OBR’s November 2025 forecast projected real household disposable income per person to grow by around 0.25% annually over its forecast period. That was considerably below the previous decade’s average growth of approximately 1% annually.The March 2026 outlook subsequently projected stronger economic growth from 2027. Nevertheless, households could still experience relatively modest improvements in purchasing power.This distinction matters because economic growth does not automatically mean every household experiences the same financial improvement.
3. Wage Growth Could Affect Spending Power
Wages are one of the most important factors determining household financial conditions. Stronger earnings can help families manage higher costs, while slower wage growth can limit discretionary spending.The OBR’s March 2026 forecast expected nominal weekly earnings growth to slow to around 2.25% annually over the medium term. It attributed this partly to a loosening labour market and lower inflation.If wages continue increasing faster than consumer prices, households could experience improvements in real purchasing power. However, households with weaker wage growth could experience different outcomes.Workers should therefore consider their own employment sector rather than relying solely on national wage averages.
4. Employment Conditions Could Influence Household Security
Employment provides the primary source of income for many households. Changes in vacancies, unemployment, working hours, and wage growth can therefore have substantial effects on family finances.The OBR expects unemployment to remain around 5% until 2027 before gradually declining toward its estimated equilibrium rate. It also expects the employment rate to remain broadly flat over the forecast period.A softer labour market could make job changes more difficult for some workers. It may also influence wage negotiations and household confidence about major purchases.However, labour-market conditions can differ significantly between industries and regions. National figures should therefore be treated as broad indicators rather than individual predictions.
5. Mortgage Costs Could Remain Important
Interest rates can affect homeowners through mortgage payments and potential refinancing costs. Households reaching the end of fixed-rate arrangements may need to consider prevailing mortgage rates when refinancing.The March 2026 OBR forecast expected Bank Rate to fall from 3.75% to around 3.3% by late 2026. It then projected Bank Rate gradually increasing toward 4% by the end of 2030.
These are forecasts rather than guaranteed outcomes. Actual interest rates depend on inflation, economic activity, financial markets, and decisions by the Bank of England.Mortgage borrowers should therefore assess their individual circumstances and refinancing dates when planning household finances.
6. Renters Could Face Continuing Housing Costs
Rent represents a major household expense for many UK residents. Changes in employment, property supply, demand, and household income can influence rental affordability.Economic challenges can affect renters through several channels. Higher household expenses can reduce money available for rent, while changes in local employment can affect housing demand.
Rental conditions also vary substantially across the UK. London and other major cities can have very different housing markets compared with smaller towns and rural areas.Households should therefore consider local rental conditions rather than applying national economic trends uniformly.
7. Energy Costs Could Influence Household Spending
Energy prices can have a direct effect on household budgets. Electricity and gas costs influence both essential expenditure and the amount households have available for other purchases.The OBR’s March 2026 forecast expected lower wholesale energy prices and government measures affecting energy bills to contribute to lower inflation. It projected CPI inflation at 2% from 2027 onwards.
However, energy markets remain exposed to international developments. Geopolitical events, supply disruptions, wholesale prices, and currency movements can all influence future household energy costs.Energy efficiency can also affect individual exposure to price changes. Better-insulated homes may require less energy for heating during colder periods.
8. Food Prices Could Continue Affecting Household Budgets
Food represents a significant part of household spending, particularly for families with children. Even when food inflation declines, previous price increases can leave food considerably more expensive than several years earlier.The OBR expected food price inflation to ease as global prices become more favourable. However, it also identified international developments as potential risks around the inflation outlook.
Households may therefore continue adjusting shopping habits, product choices, and meal planning. Lower inflation would reduce the pace of future price increases without necessarily reversing previous increases.Food spending can vary considerably depending on household size, dietary requirements, location, and purchasing habits.
9. Taxes Could Affect Disposable Income
Changes in taxation can influence household disposable income. The impact depends on income levels, employment arrangements, property ownership, savings, investments, and other personal circumstances.The OBR has highlighted fiscal drag resulting from frozen personal tax thresholds. When wages rise while thresholds remain unchanged, more income can become subject to higher tax rates over time.
This can affect households even when tax rates themselves do not change. Workers receiving nominal pay increases may therefore experience smaller increases in after-tax income.Households should consider net income rather than gross salary when assessing their expected financial position.
10. Public Services Could Affect Household Finances
Households do not experience government spending only through direct payments. Public services such as healthcare, education, transport, childcare, and local services can have significant financial value.Government spending plans therefore matter for household budgets. The 2026 Spring Forecast highlighted measures involving childcare, breakfast clubs, energy costs, and other areas affecting household finances.
Changes in public services can affect families differently. For example, households with young children may have different financial considerations from retired households.The availability and quality of services can also influence household decisions about employment, childcare, education, and location.
11. Childcare Costs Could Influence Working Families
Childcare costs can represent a substantial expense for families with young children. Government-funded childcare provision can therefore influence household disposable income and employment decisions.The government has highlighted funded childcare as part of its household support measures. The Spring Forecast 2026 specifically referenced 30 hours of free childcare and other family-related support.
The practical effect depends on eligibility, childcare availability, working patterns, and local provision. Not every household will experience the same financial benefit.Families should check current official eligibility requirements because support arrangements can change over time.
12. Transport Costs Could Affect Household Budgets
Transport expenses include fuel, public transport fares, vehicle insurance, maintenance, parking, and commuting costs. Economic conditions can influence several of these expenses.Government policies can also affect transport costs. The OBR’s November 2025 assessment identified a temporary fuel duty freeze and rail fare measures among policies affecting inflation.
For households commuting long distances, relatively small changes in transport costs can have significant annual effects.Remote working can reduce transport expenses for some workers, while employees requiring regular commuting may remain more exposed to transport costs.
13. Savings Could Become More Important
Economic uncertainty can encourage households to maintain stronger emergency savings. A financial reserve can help families manage unexpected expenses, employment changes, or temporary income reductions.Interest rates also influence the returns households receive from savings accounts and other interest-bearing products. However, actual returns vary between products and providers.
Households should consider inflation when assessing savings. If savings grow more slowly than consumer prices, their purchasing power may decline even when the account balance increases.Financial circumstances differ substantially, so households should consider their own objectives and risk tolerance.
14. Borrowing Costs Could Influence Household Decisions
Interest rates affect more than mortgages. Personal loans, credit cards, car finance, and other borrowing arrangements can also be influenced by broader financial conditions.If borrowing costs remain elevated, households may postpone major purchases or reduce reliance on credit. Lower borrowing costs could provide greater flexibility for some borrowers.
However, individual rates depend on the product, lender, credit circumstances, and loan terms.Households considering significant borrowing should calculate total repayment costs rather than focusing only on advertised monthly payments.
15. Housing Decisions Could Become More Careful
Economic uncertainty can influence decisions about buying, selling, renovating, or moving home. Households may delay major property decisions when employment or interest-rate conditions appear uncertain.The OBR’s March 2026 forecast includes a housing-market assessment alongside its wider economic outlook. Its projections reflect assumptions about interest rates, household incomes, and broader economic conditions.
Property markets vary considerably by region and property type. National economic indicators therefore cannot determine the value or affordability of an individual home.Households should consider local prices, mortgage affordability, employment security, and long-term housing needs.
16. Pensioners Could Experience Different Effects
Older households can experience economic changes differently because their income sources often differ from those of working-age households.Pension income, savings returns, housing costs, energy bills, and healthcare requirements can all influence financial circumstances during retirement.
Inflation is particularly important for pensioners because many household expenses are unavoidable. Changes in food, energy, housing, and healthcare-related costs can affect fixed or limited incomes.The overall impact therefore depends on the combination of state pension income, private pensions, savings, investments, housing circumstances, and household spending.
17. Families Could Adjust Their Spending Habits
Economic pressure can influence household decisions about entertainment, holidays, dining, clothing, subscriptions, and other discretionary spending.When essential costs rise faster than income, households may reduce spending on non-essential products. This can affect businesses that depend heavily on discretionary consumer expenditure.
Conversely, improving real incomes can support greater spending on leisure, hospitality, travel, and household goods.Consumer behaviour is therefore an important connection between household finances and wider economic performance.
18. Regional Differences Could Remain Significant
Economic conditions are not identical across the UK. Employment opportunities, wages, house prices, rents, transport costs, and public services can vary considerably between regions.A household in London may face different housing expenses from a family in northern England. Similarly, employment opportunities can vary between regions depending on dominant industries.
National economic statistics provide important context, but local circumstances remain essential when assessing household finances.Households should therefore consider regional labour markets and housing conditions alongside national economic indicators.
19. Economic Growth Could Provide Some Support
Economic challenges do not necessarily mean every household will experience worsening financial conditions. Economic growth can support employment, business activity, wages, and investment.The OBR’s March 2026 forecast expects real GDP growth to average 1.6% annually from 2027 through 2030. It expects productivity growth to strengthen while the negative output gap closes.
If productivity improves, businesses may have greater capacity to increase output and potentially create additional economic opportunities.The distribution of those benefits remains uncertain. Household outcomes can differ according to employment, income, region, and individual circumstances.
20. UK Households Watch During 2027
Households should monitor inflation, wage growth, employment conditions, interest rates, energy prices, taxation, housing costs, and government support during 2027.The OBR emphasizes that economic forecasts contain uncertainty. Its March 2026 outlook identifies risks from inflation expectations, international developments, energy prices, and monetary policy.
Households can respond to uncertainty by reviewing regular expenses, maintaining appropriate emergency savings, and understanding their borrowing commitments.It can also be useful to distinguish between temporary price changes and longer-term changes in household income. This distinction can improve financial planning.
Conclusion
Economic challenges could affect UK households during 2027 through inflation, wages, employment, housing, energy costs, taxation, borrowing, savings, and public services. However, the effects are unlikely to be identical across every household.The current OBR forecast provides a more positive growth outlook from 2027, with inflation expected to settle around 2%. Nevertheless, wage growth and household disposable-income growth remain important factors when considering living standards.
FAQ
How could economic challenges affect UK household budgets in 2027?
Economic challenges could increase pressure on household budgets through living costs, housing expenses, taxes, and essential bills.
Could UK households face higher living costs in 2027?
Some households could experience higher costs if prices for energy, food, transport, housing, or other essentials increase.
How might interest rates affect UK households in 2027?
Interest rate changes could influence mortgage payments, borrowing costs, savings returns, and household financial planning.
Could economic challenges affect household employment in 2027?
Economic uncertainty could influence recruitment, wage growth, working hours, and employment opportunities across different industries.
What can UK households do to prepare for economic challenges in 2027?
Households can review budgets, manage debts carefully, build emergency savings, and monitor changes affecting regular expenses.